The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Professional indemnity insurance for consultants is usually arranged on a claims-made basis, which means timing matters. This guide explains claims-made cover, retroactive dates, notification obligations, continuous cover and run-off cover for Australian consultants.
Professional indemnity insurance is designed to help protect consultants against claims alleging financial loss caused by their professional advice, services, errors, omissions or negligence. For Australian consultants, understanding what a policy covers is important, but understanding when it responds can be just as important.
Many professional indemnity policies operate on a claims-made basis. This means the policy that may respond is generally the one in force when the claim is made or when a notifiable circumstance is reported, not necessarily the policy you held when the work was originally performed. That timing can affect consultants who are buying cover for the first time, renewing a policy, switching insurers, cancelling cover, changing business structure or retiring from consulting.
This article explains claims-made professional indemnity insurance, retroactive dates, notification obligations and run-off cover in practical terms. It is general information only and does not replace reading the policy wording or seeking advice about your own business circumstances.
Why professional indemnity insurance matters for consultants
Consultants are often engaged for their judgement, specialist knowledge and recommendations. A client may rely on your advice when making operational, financial, technology, management, compliance or strategic decisions. If the client later alleges that your work caused them loss, the cost of responding can be significant even where the allegation is disputed.
Professional indemnity insurance may help with covered legal defence costs, settlements or compensation amounts, subject to the terms, conditions, exclusions, excesses and limits of the policy. It can also support a more structured response to a dispute, because insurers usually have claims teams and panel lawyers experienced in professional liability matters.
The need for cover may also arise from client contracts, industry standards, professional association requirements or tender conditions. The appropriate cover depends on your services, client base, contractual obligations, claims history and the insurer's underwriting criteria. For broader information about consultant insurance options, you can visit Consultants Insurance Online.
Claims-made professional indemnity: the key concept
A claims-made professional indemnity policy generally responds to claims first made against you and notified to the insurer during the period of insurance, provided the claim is otherwise covered by the policy. Some policies also allow you to notify circumstances that could reasonably give rise to a future claim. If properly notified, those circumstances may be treated in accordance with the policy terms if a claim later develops.
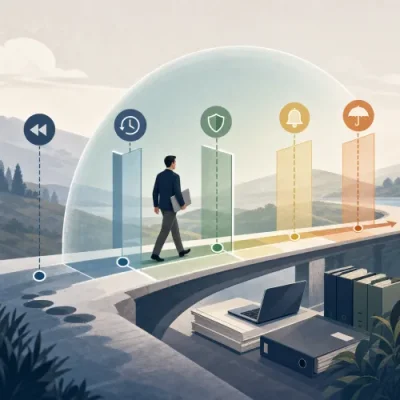
This is different from some other forms of insurance that may respond based on when an incident occurred. With professional indemnity, the key dates commonly include:
- When the professional work was performed. This may be months or years before a client complains.
- The policy retroactive date. This can limit how far back the policy will look for covered work.
- When you first became aware of a claim or circumstance. This can affect notification obligations and whether a later insurer will treat the matter as a known issue.
- When the claim or circumstance is notified to the insurer. Timely notification is often a core policy requirement.
- The policy expiry or cancellation date. Claims made after cover ends may not be covered unless run-off or replacement cover applies.
| Concept |
Why it matters for consultants |
| Claims-made cover |
The policy usually needs to be active when the claim is made or the circumstance is notified. |
| Retroactive date |
Claims relating to work before this date may be excluded or restricted. |
| Continuous cover |
Maintaining uninterrupted cover can reduce the risk of gaps when claims emerge later. |
| Notification obligations |
Delays or failure to notify may affect how the insurer assesses the claim. |
| Run-off cover |
Cover may be needed after you stop consulting because claims can arise after work is completed. |
How retroactive dates work
A retroactive date is the date from which the policy may cover past professional services, subject to the policy wording. If a claim arises from work performed before the retroactive date, the policy may not respond.
For example, if your policy has a retroactive date of 1 July 2024 and a client claim relates to consulting work performed in 2023, the claim may fall outside the policy's retroactive cover. If the retroactive date is shown as "unlimited" or "none", the policy may not impose a specific date limit for past work, although other exclusions and conditions can still apply.
Retroactive dates are especially important when:
- you are buying professional indemnity insurance for the first time after already providing services;
- you are switching from one insurer to another;
- you are changing from sole trader to company structure or restructuring your consulting business;
- you have had a break in cover;
- you are adding new consulting services or new business activities; or
- you are renewing after a claim, complaint or known circumstance.
When comparing policies, do not focus only on the premium and limit of indemnity. Check whether the retroactive date preserves the protection you expected for prior work. A cheaper policy may not provide the same historical protection if the retroactive date is more restrictive.
Continuous cover and avoiding gaps
Because professional indemnity insurance is commonly claims-made, continuity can be important. A claim may arise long after the advice was given, the report was delivered or the project ended. If your cover has lapsed, been cancelled or replaced with a policy that excludes prior work, you may face uncertainty about whether any insurer will respond.
Common gap risks include:
- Letting a policy lapse between renewals. Even a short gap can create complications if a claim or circumstance emerges during that period.
- Switching insurers without checking prior work cover. A new insurer may apply a new retroactive date or exclude known circumstances.
- Changing business entities. A policy issued to a new company may not automatically cover liabilities of a previous sole trader, partnership or related entity.
- Cancelling cover when a contract ends. The end of a project does not always mean the end of potential liability.
- Assuming client sign-off ends all risk. A client may only discover an alleged problem later.
Consultants should review renewal documents carefully and keep records of previous policies, retroactive dates, endorsements and correspondence. If you are unsure whether a change could create a gap, ask the insurer or broker before the current policy expires.
Notification obligations: claims and circumstances
Professional indemnity policies usually require prompt notification of claims. Many also require or encourage notification of circumstances that could reasonably give rise to a claim. The wording matters, because a "claim" and a "circumstance" may be defined differently from one policy to another.
A claim may include a written demand, legal proceeding, formal complaint or allegation that seeks compensation or another remedy. A circumstance may be an incident, error, client concern, project failure or dispute that has not yet become a formal claim but could reasonably lead to one.
Examples of situations that may require careful consideration include:
- a client alleges your advice caused financial loss;
- a client refuses to pay and says your work was defective;
- you discover a material error in a report already provided to a client;
- a client threatens legal action, even informally;
- you receive a letter of demand or solicitor's correspondence;
- a project outcome suggests your professional services may be questioned; or
- you become aware of a regulatory, contractual or compliance issue connected with your advice.
If something occurs that may become a claim, avoid assuming it is too minor to notify. Late notification can complicate the insurer's position and may affect cover depending on the facts and policy terms. You should also avoid admitting liability, agreeing to compensation, making settlement offers or incurring significant legal costs without insurer consent unless the policy or circumstances permit it.
Good file notes, written confirmations, version-controlled documents and records of client instructions can be important if a claim arises. For broader risk controls, including record keeping and client communication practices, see Building a Resilient Consulting Business: Tips for Risk Reduction.
What professional indemnity may cover
Professional indemnity insurance is not identical across insurers, occupations or policy wordings. However, subject to the policy terms, it may cover claims connected with professional services such as:
- alleged negligence in advice, analysis or recommendations;
- errors or omissions in professional work;
- misstatements or misleading professional advice;
- failure to exercise reasonable care or skill;
- breach of professional duty;
- certain allegations of defamation, breach of confidentiality or intellectual property infringement, where included; and
- legal defence costs associated with covered claims.
The exact scope depends on how the policy defines professional services, insured persons, claims, losses, defence costs and exclusions. A management consultant, IT consultant, HR consultant, marketing consultant and engineering consultant may have different risk profiles and may need different wording.
Common exclusions and limitations
Professional indemnity insurance does not cover every business dispute. Common exclusions or limitations may relate to:
- intentional wrongdoing, fraud or dishonest conduct;
- criminal acts or penalties that cannot legally be insured;
- known claims or circumstances that existed before the policy began and were not disclosed or accepted;
- work performed before the retroactive date;
- contractual liabilities that go beyond the consultant's ordinary professional duty;
- refunds of fees or poor commercial outcomes not caused by a covered professional breach;
- bodily injury or property damage, which may require public liability cover;
- employment disputes, which may require separate management liability or employment practices cover;
- cyber incidents, unless expressly included or covered by a separate cyber policy; and
- claims outside the policy territory or jurisdiction limits.
Because exclusions vary, consultants should read the product disclosure statement, policy wording, schedule and endorsements. Pay attention to definitions, sub-limits, excesses, conditions precedent and notification requirements.
Run-off cover for consultants
Run-off cover is professional indemnity cover arranged for claims made after you stop providing professional services, cancel active trading cover or sell, close or restructure the business. It recognises that claims can arise after the work has been completed.
Run-off cover may be relevant if you:
- retire from consulting;
- close your consulting practice;
- sell your business or transfer clients to another provider;
- move from contracting to employment and no longer maintain your own policy;
- wind up a company or partnership;
- change business structure and the old entity still has potential liabilities; or
- stop offering a higher-risk service but may still face claims from past work.
The length of run-off cover needed depends on factors such as your contracts, the type of consulting work, potential limitation periods, professional association requirements and client expectations. There is no single period that suits every consultant. Some contracts may also require cover to be maintained for a period after project completion.
Run-off terms, availability and pricing depend on insurer criteria and individual circumstances. Some insurers may offer annual run-off renewals, while others may apply specific conditions. Before cancelling a policy, discuss whether run-off is available and what it will and will not cover. If you need help reviewing policy wording, entity changes or run-off arrangements, you can speak with insurance professionals through the Brokers page.
Changing insurers without losing important protection
Consultants often compare providers at renewal, particularly if their services, revenue, client contracts or risk profile have changed. Switching insurers can be appropriate in some circumstances, but it should be handled carefully with claims-made policies.
Before moving to a new policy, check:
- whether the new policy keeps the same retroactive date;
- whether any known claims or circumstances must be disclosed;
- whether any pending client disputes should be notified to the current insurer before expiry;
- whether the new policy covers the same professional services;
- whether the limit of indemnity and excess remain suitable for your work and contracts;
- whether defence costs are included within the limit or in addition to the limit;
- whether there are new exclusions, sub-limits or endorsements; and
- whether all relevant entities, directors, employees, contractors and past principals are insured.
Do not assume a replacement policy is equivalent simply because it has the same headline limit. The policy wording, retroactive date and exclusions may be materially different.
Buying or renewing consultant PI insurance: practical checklist
When buying, renewing or changing consultant PI insurance in Australia, it may help to prepare the following information:
- a clear description of your consulting services;
- your business structure and any previous trading names or entities;
- revenue, major clients and contract types;
- any overseas clients or work performed outside Australia;
- details of subcontractors or other professionals you engage;
- client contract insurance requirements;
- previous claims, complaints or circumstances;
- your current retroactive date and policy history;
- risk management procedures, quality controls and record keeping practices; and
- planned changes to services, staffing or client work.
When reviewing quotes, consider more than the premium. Relevant factors include the insurer's appetite for your profession, claims handling approach, policy definitions, exclusions, limit of indemnity, excess, retroactive date, run-off options and any endorsements specific to your consulting field.
Making a professional indemnity claim
If a claim or potential claim arises, the first step is to read your policy and notify the insurer or broker promptly. The exact process depends on the insurer and wording, but consultants can generally expect to:
- Gather key information. This may include contracts, scopes of work, proposals, reports, emails, file notes, meeting records, invoices and client communications.
- Notify the insurer or broker. Provide a factual summary and copies of relevant documents. Avoid speculation or admissions of liability.
- Follow insurer instructions. The insurer may appoint claims staff, lawyers or other specialists to assess the matter.
- Preserve evidence. Keep records secure and avoid deleting files, messages or project materials.
- Manage client communication carefully. Do not agree to settlement, refunds or compensation without checking the policy requirements and insurer position.
- Cooperate with the claim assessment. The insurer may request further documents, interviews or explanations as the matter progresses.
Claims can involve coverage assessment as well as the underlying client dispute. The insurer will consider whether the claim falls within the policy, whether any exclusions apply, whether the matter was notified in time and whether all policy conditions have been met.
Reducing the chance of PI disputes
Insurance is one part of risk management. Consultants can reduce the likelihood or severity of disputes by using clear engagement processes and maintaining evidence of professional decision-making.
Useful practices may include:
- using written scopes of work and engagement letters;
- confirming assumptions, exclusions and client responsibilities;
- documenting material advice and recommendations;
- keeping records of client approvals and changes in scope;
- using quality assurance checks for reports and deliverables;
- raising issues early where project risks change;
- reviewing contracts before accepting broad indemnities or unrealistic obligations;
- keeping professional qualifications, licences or memberships current where relevant; and
- reviewing insurance whenever your services or client profile changes.
These steps do not remove all risk, but they can make expectations clearer and assist if a claim needs to be defended.
Key takeaways for Australian consultants
Claims-made professional indemnity insurance requires consultants to think about timing. The policy in force when a claim is made or a circumstance is notified may be central to whether cover is available. Retroactive dates can affect protection for past work, and run-off cover may be needed after you stop consulting or change business structure.
Before buying, renewing, switching or cancelling professional indemnity insurance, review the policy wording carefully and consider how it treats prior work, known circumstances, notification obligations and run-off. If your contracts, services or business structure are complex, consider seeking professional assistance before making changes to your cover.
Published: Saturday, 20th Dec 2025
Author: Paige Estritori



No comments yet. Be the first to share your thoughts.